Open Hours
Monday – Friday: 9am – 5pm
Saturday – Sunday: Closed
Closed for lunch: 12pm – 1pm
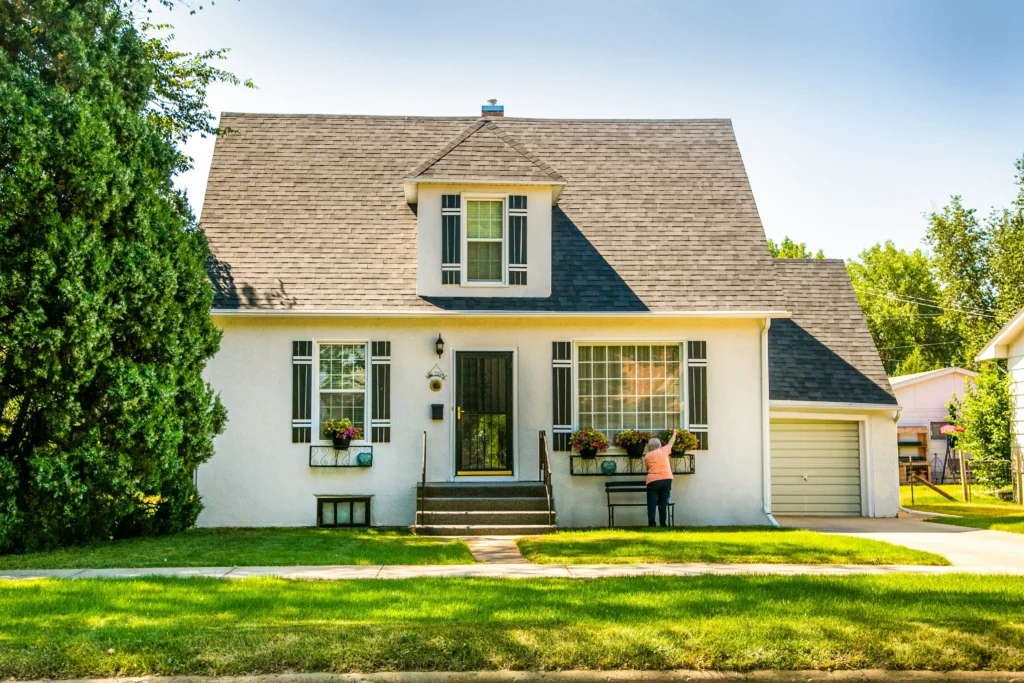
Your home is the single largest investment you’ll ever make. White’s Insurance Agency is an independent insurance agent serving Southwest Missouri — which means we shop homeowners insurance quotes from multiple carriers to find the property insurance coverage that fits your home, your budget, and your life. No pressure. No jargon. Just the right policy.
Most homeowners in Southwest Missouri renew their house insurance every year without a second look — and many are unknowingly underinsured. Your home’s replacement cost changes over time. Contents depreciate. Coverage limits that made sense five years ago may leave you exposed today. And if disaster strikes — a fire, a severe storm, a liability claim — you’ll find out too late that your policy didn’t go far enough.
White’s Insurance Agency reviews your homeowners insurance coverage from the ground up. As your independent insurance agent, we compare property insurance policies across multiple carriers, explain the difference between replacement cost and actual cash value, and make sure your dwelling coverage, personal property coverage, and liability coverage are all where they need to be — before you ever need to file a claim.
Homeowners insurance exists to protect you from the financial devastation of losing your home. But a policy that’s priced too low, carries the wrong coverage limits, or excludes the right perils can leave you absorbing costs you never expected.
A standard homeowners insurance policy is made up of several distinct coverage types — each one protecting a different part of your home, your belongings, and your financial exposure. Here’s what each component covers, in plain language.
Dwelling coverage is the core of your homeowners insurance policy. It pays to repair or rebuild the physical structure of your home — walls, roof, floors, built-in appliances, and attached structures like a garage — if it’s damaged or destroyed by a covered peril.
What It Covers: Fire, lightning, windstorm, hail, explosion, vandalism, and other named perils. Southwest Missouri’s severe weather — including tornadoes, hail, and ice storms — makes adequate dwelling coverage essential.
Coverage Limit: Your dwelling coverage limit should reflect the full cost to rebuild your home at current construction costs — not its market value. We help you calculate an accurate rebuild cost so you’re not underinsured.
Replacement Cost vs. Actual Cash Value: Replacement cost coverage pays to rebuild without factoring in depreciation. Actual cash value (ACV) policies subtract depreciation and typically result in a lower payout. We recommend replacement cost coverage for most policyholders.
Attached Structures: Garages, decks, and covered porches attached to your home are typically covered under dwelling coverage.
Personal property coverage — sometimes called contents insurance — protects the belongings inside your home: furniture, clothing, electronics, appliances, and more. If your possessions are damaged, destroyed, or stolen, personal property coverage helps pay to repair or replace them.
What It Covers: Theft, fire, smoke, vandalism, water damage from plumbing failures, and other covered perils. Some personal property coverage even extends to belongings outside the home — in your car, at a storage unit, or while traveling.
Replacement Cost vs. Actual Cash Value: Like dwelling coverage, you can choose between replacement cost (pays what it costs to buy a comparable new item today) and actual cash value (subtracts depreciation). Replacement cost is the better protection.
High-Value Items: Standard personal property coverage has sub-limits for categories like jewelry, firearms, art, and collectibles. If you own high-value items, we’ll discuss adding an endorsement or rider to ensure full coverage.
Home Inventory: We recommend keeping a documented home inventory — photos or video of your belongings — to streamline the insurance claim process after a loss.
Personal liability coverage protects you if someone is injured on your property or if you accidentally cause damage to someone else’s property. It covers legal defense costs, medical expenses, and settlement or judgment amounts — up to your policy’s coverage limit.
What It Covers: A guest slips and falls in your home. Your child accidentally breaks a neighbor’s window. Your dog bites someone on your property. Personal liability coverage steps in to handle the financial and legal consequences.
Coverage Limits: Standard homeowners policies offer $100,000 in liability coverage — but many insurance agents recommend $300,000 or more. If your assets exceed your liability limit, an umbrella policy can provide an additional layer of protection.
Medical Payments Coverage: Most homeowners policies include a small amount of medical payments coverage (sometimes called MedPay), which pays for minor injuries to guests on your property regardless of fault — helping prevent small incidents from becoming costly liability claims.
Risk Management: Adequate liability coverage is one of the most important — and most often overlooked — parts of a homeowners insurance policy. We make sure your limits reflect your actual exposure.
If a covered loss makes your home temporarily uninhabitable, loss of use coverage pays for your additional living expenses while repairs are made. This can include hotel bills, rental reimbursement, restaurant meals, and other costs beyond your normal living expenses.
What It Covers: Additional living expenses above your normal costs while your home is being repaired or rebuilt after a covered loss. Examples: hotel or rental costs, dining out, laundry, and pet boarding.
Coverage Limit: Loss of use coverage is typically set as a percentage of your dwelling coverage — often 20–30%. We review this limit against your actual cost of living to make sure it’s sufficient.
Temporary Housing: In a severe loss scenario — like a tornado or major fire — loss of use coverage can mean the difference between a manageable situation and a financial crisis while your home is rebuilt.
Rental Reimbursement Note: If you rent out a portion of your home, fair rental value coverage (a related protection) may apply. Ask your agent about your specific situation.
Other structures coverage extends your homeowners insurance to structures on your property that aren’t attached to your main home — fences, detached garages, sheds, workshops, barns (for non-farming use), and other outbuildings.
What It Covers: Damage to detached structures from covered perils — fire, windstorm, hail, vandalism, and more.
Coverage Limit: Other structures coverage is typically set at 10% of your dwelling coverage limit. If you have significant outbuildings or a detached garage, we’ll review whether your limit is adequate.
Farm Structures: If you have a working farm operation, agricultural structures may require a separate farm insurance policy rather than coverage under your homeowners policy. White’s writes both — we’ll make sure you have the right policy for each structure
This is one of the most important things to understand about your homeowners insurance policy: standard house insurance does not cover flood damage or earthquake damage. These require separate policies — and many Missouri homeowners don’t find out until after a loss.
Flood Insurance: Standard homeowners insurance excludes flood damage — even if the flood is caused by a severe storm or rising creek. Flood insurance is available through the National Flood Insurance Program (NFIP) or private carriers. If your property is in or near a flood zone, this coverage is critical.
Flood Risk Assessment: We help you understand your property’s flood risk using flood zone maps and local data. Even properties outside designated flood zones can experience flood damage — and flood insurance may still make sense.
Earthquake Insurance: Missouri sits near the New Madrid Seismic Zone — one of the most seismically active regions in the continental United States. Standard homeowners policies do not cover earthquake damage. Earthquake insurance can be added as a separate policy or endorsement.
Natural Disaster Coverage: For Southwest Missouri homeowners, we strongly recommend a conversation about both flood and earthquake exposure. We’ll help you assess your risk and determine whether additional coverage makes sense for your property.
A standard Missouri homeowners insurance policy typically covers: damage to your home’s structure (dwelling coverage) from named perils like fire, windstorm, and hail; personal property (contents insurance) for your belongings; personal liability coverage if someone is injured on your property; loss of use coverage if your home becomes temporarily uninhabitable; and medical payments coverage for minor guest injuries. It does not cover flood damage or earthquake damage — those require separate policies.
No. Standard homeowners insurance policies specifically exclude flood damage. Flood insurance must be purchased separately — either through the National Flood Insurance Program (NFIP) or a private carrier. Missouri has experienced significant flood events, and even properties outside of designated flood zones can be affected. White’s Insurance Agency can help you assess your flood risk and find the right flood insurance coverage.
Replacement cost coverage pays what it would cost to repair or replace damaged property with a comparable new item — without depreciation. Actual cash value (ACV) coverage subtracts depreciation from the payout. For example, if a hailstorm destroys a 12-year-old roof, ACV pays the current depreciated value of that roof — which may be a fraction of what a new roof costs. Replacement cost coverage closes that gap. We recommend replacement cost coverage for both dwelling and personal property whenever possible.
White’s Insurance Agency has served families, farmers, and businesses across Southwest Missouri for four generations. As an independent insurance agency, we shop multiple carriers to find you the right coverage at the best price — with the personal service you deserve.
White Insurance Agency works hard for their clients to find the best coverage for an affordable price that will meet your family’s needs. I recommend them to anyone. You’re respected and treated like family. Thanks Lea for listening and working hard to lower our rates.
Really the best place to visit the staff is very friendly and the director Amanda is very sweet and always attentive. We do reenactments once a year and I always look forward to it every year. The whole family participates and it is family friendly. Little tip bring some ear plugs for the little one they tend to be scared of the loud canyon so they don't miss out. And when you visit you must sign in your name and where you're from. Help support the museum.